Warning Signs You’re Overly Frugal in Your Golden Years
Retirement is meant to be a season of freedom, comfort, and enjoyment after decades of work, yet excessive frugality can quietly sabotage this stage of life. Being budget-conscious is admirable, but when it crosses into extreme penny-pinching, it compromises both physical and mental health, limits meaningful social interactions, and erodes overall well-being.
Many retirees focus on saving to an extreme, avoiding expenses that would enhance quality of life or protect them from risk, ultimately turning financial caution into a form of self-imposed deprivation. Understanding these warning signs helps retirees recalibrate their approach to money, ensuring that their hard-earned savings enhance rather than diminish their golden years.
Declining Social Interaction to Cut Costs
One of the most visible signs of extreme frugality in retirement is avoiding social events or gatherings purely to save money. Retirees who consistently decline invitations to family celebrations, community activities, or casual outings may appear socially disciplined, but the hidden cost is profound.
Social isolation is strongly linked to declines in cognitive function, increased stress, and higher rates of depression and anxiety in older adults. While frugality may preserve short-term finances, the long-term health consequences of reduced social engagement often outweigh the money saved.
Recalibrating this approach involves planning for social interactions within a structured budget. By allocating funds specifically for community events, dining, or leisure activities, retirees can maintain meaningful relationships without compromising financial security. This practice reinforces emotional resilience, combats loneliness, and supports mental and physical health, demonstrating that smart financial planning can coexist with a vibrant social life.
Obsessive Bargain-Hunting and Sacrificing Quality
Pursuing the lowest possible price for every purchase, regardless of quality or necessity, may initially feel prudent, but it often leads to higher cumulative costs. Low-quality items frequently require replacement or repair, which negates any perceived savings.
Moreover, obsessively hunting for bargains can create psychological stress, reinforce scarcity thinking, and prevent retirees from enjoying their daily lives or from experiencing genuine satisfaction.
Effective frugality integrates value-based decision-making. Investing in durable, reliable products minimizes replacement cycles, reduces long-term expenses, and increases satisfaction. Strategic spending balances cost and quality, ensuring that financial restraint enhances rather than diminishes the quality of life.
Neglecting Necessary Healthcare

Failing to invest in necessary healthcare, whether by skipping doctor visits, delaying tests, or rationing medications, is one of the most dangerous manifestations of extreme frugality. The immediate savings gained from avoiding appointments or prescriptions are minimal compared to the potential costs of preventable complications or emergency interventions.
Chronic health conditions often worsen when not monitored, and delayed care can lead to hospitalizations, reduced mobility, and diminished independence; ironically, increasing long-term financial burdens while eroding quality of life.
Prioritizing health expenditures is an essential component of financial wisdom in retirement. Investing in preventive care, regular checkups, and prescribed medications protects both longevity and quality of life. Financial planning should include a healthcare buffer to accommodate unexpected needs, ensuring that frugality does not compromise well-being.
Extreme Transportation Cost-Cutting
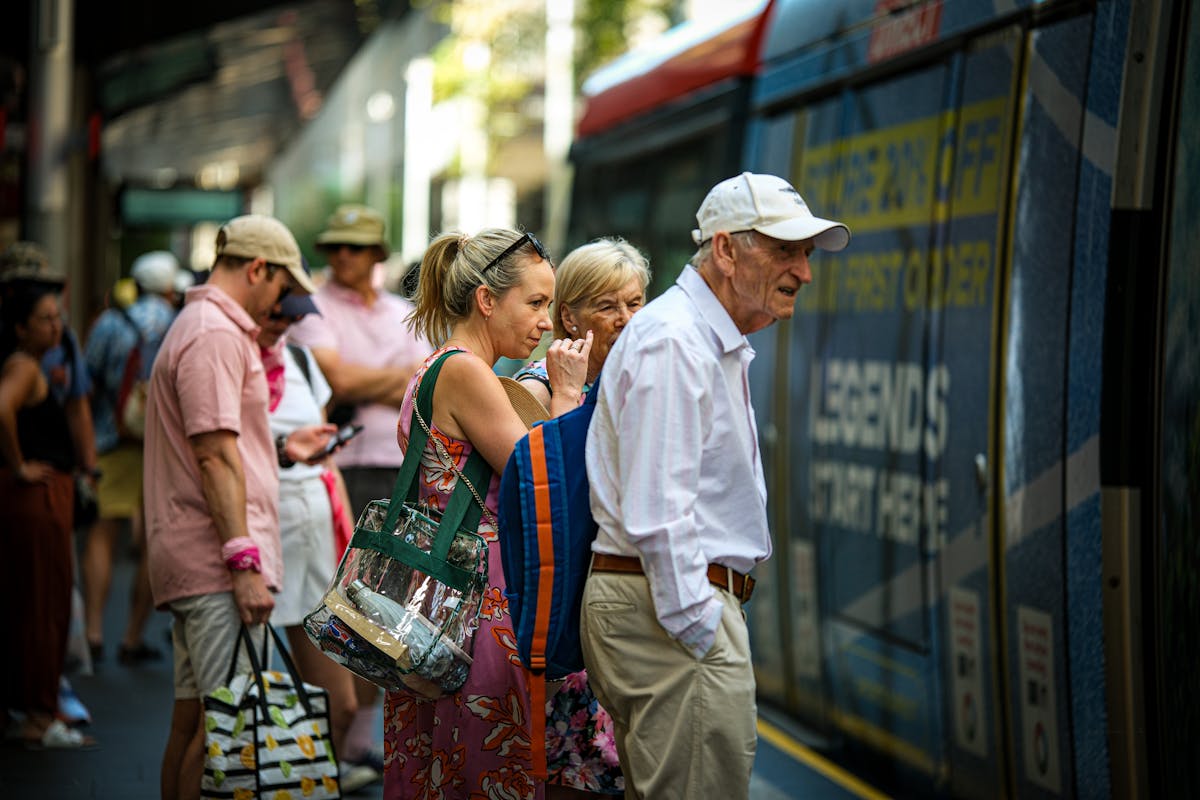
While walking or using public transportation can be practical and environmentally friendly, insisting on these options to save money under all circumstances can be counterproductive in retirement. Overextending physical effort or ignoring safety considerations in inclement weather or unsafe areas introduces unnecessary risk.
Such extreme measures can reduce mobility, increase fatigue, and ultimately compromise independence, a critical factor in maintaining a high quality of life in retirement. Balanced financial decision-making requires evaluating convenience, safety, and cost simultaneously. Occasional use of rideshares, taxis, or personal vehicles for necessary errands ensures that savings do not come at the expense of well-being.
Transportation choices should reflect a thoughtful balance, acknowledging that small investments in comfort or safety protect both physical health and long-term financial outcomes by preventing accidents or medical emergencies caused by overexertion.
Avoidance of Generosity and Sharing
Refusing to contribute financially to family, friends, or charitable causes, even when resources allow, demonstrates a restrictive approach to money that diminishes fulfillment. Generosity during retirement is not only a reflection of financial capability but also a source of personal satisfaction, social connection, and purpose.
Balanced generosity strengthens relationships and reinforces emotional well-being. Thoughtful financial contributions, aligned with one’s values, allow retirees to experience the positive impact of their resources without compromising security.
Retirees who withhold support purely out of extreme frugality risk trading emotional enrichment for minimal monetary savings, undermining the holistic objectives of financial planning in later life.
Chronic Stress Over Minor Expenses
Constant anxiety about every small expenditure indicates an unhealthy relationship with money that extends beyond practical budgeting. Obsessive focus on pennies, coupons, or trivial purchases generates cognitive strain and emotional fatigue, reducing overall quality of life.
Retirement is intended to be a period of reduced stress and increased enjoyment, yet excessive worry over minor costs can overshadow financial stability and create unnecessary tension.
Developing a structured budget with designated discretionary spending mitigates anxiety while preserving financial oversight. Allowing for modest indulgences fosters psychological well-being, prevents resentment, and reinforces a healthy balance between prudence and enjoyment.
Conclusion
Extreme frugality in retirement is a paradox: it preserves money while simultaneously diminishing life satisfaction, health, and social engagement. Retirees must recognize when budgeting crosses the line into self-imposed deprivation, balancing caution with quality, experience, and well-being.
By addressing these warning signs, retirees can reclaim both their financial security and their freedom to enjoy the golden years. Sustainable retirement requires prudence paired with thoughtful indulgence, ensuring that the hard-earned wealth of decades is used to enrich life, not merely to conserve it.