Social Security Stops Paying Benefits to Anyone Convicted of a Crime and Sentenced to Jail or Prison for More Than 30 Days in a Row, and Payments Can Restart the Month After Release
Imagine checking your bank account and discovering that your monthly Social Security payment has disappeared. No deposit, no familiar amount, and suddenly, a lot of questions.
For Americans who are incarcerated, this can become a reality. The Social Security Administration (SSA) has rules that suspend certain benefits when someone is convicted of a crime and spends more than 30 continuous days in jail or prison.
But there’s a detail many people miss: Getting released doesn’t mean the money automatically starts arriving again.
And depending on which benefits you receive, the rules for stopping and restarting payments can look very different.
Here’s what you need to know.
Why Social Security Stops Paying Benefits During Incarceration
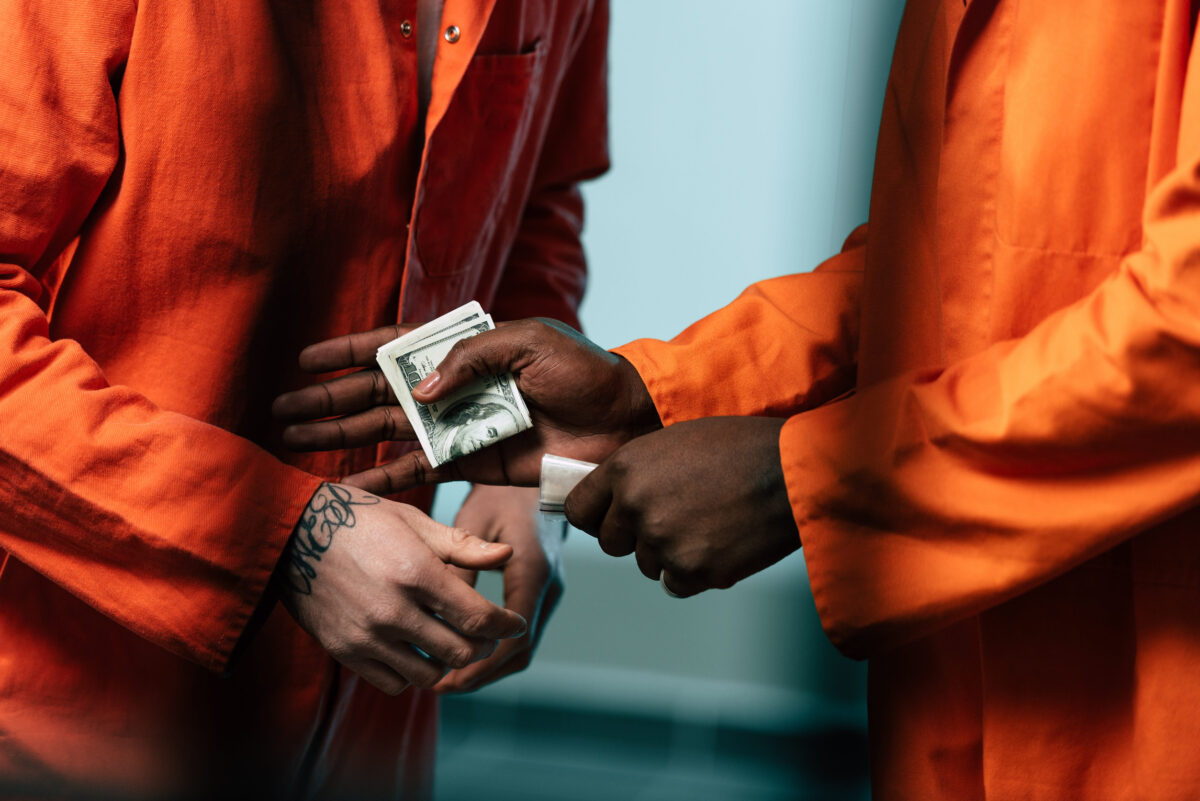
Under federal law, people receiving Social Security retirement, disability, survivor, or other covered benefits generally cannot continue collecting their own payments while serving a qualifying jail or prison sentence.
According to the Social Security Administration’s official rules, the suspension applies when someone has been convicted, sentenced, and confined in a correctional facility for more than 30 continuous days.
And no, the rule isn’t limited to serious felony convictions. Certain misdemeanor convictions can trigger it, too.
However, simply getting arrested doesn’t automatically stop retirement or Social Security Disability Insurance (SSDI) benefits.
Someone awaiting trial generally remains eligible for those payments under the ordinary incarceration rule, provided they meet all other requirements.
The important distinction is between being held before a conviction and being confined following a qualifying conviction and sentence.
The 31st Day Is Where Things Get Interesting
Here’s where the calendar becomes especially important.
Someone serving exactly 30 qualifying consecutive days generally doesn’t meet the threshold for Social Security’s ordinary prisoner suspension.
But once confinement reaches day 31, the situation changes.
And there’s another surprise.
The suspension can apply retroactively to the month qualifying confinement began, rather than simply starting on day 31.
Imagine someone enters jail on July 5 following sentencing and remains there for 60 consecutive days.
The 31-day threshold is reached in August, but Social Security can suspend benefits beginning with July.
That means a payment already deposited could eventually be considered an overpayment.
If the money keeps arriving after incarceration, don’t assume it’s automatically yours to keep.
Social Security and SSI Have Different Rules
This is probably the most important distinction in the entire process.
Regular Social Security benefits and Supplemental Security Income (SSI) don’t follow the same incarceration rules.
For Social Security retirement and SSDI, the ordinary suspension threshold is more than 30 continuous days of qualifying confinement after conviction.
SSI works differently.
A person generally cannot receive SSI for an entire calendar month spent in a public jail or prison, even without a criminal conviction.
For example, someone incarcerated throughout February could lose SSI eligibility for that month, even though February has fewer than 31 days.
There’s another important difference.
After 12 consecutive months of SSI suspension, eligibility generally terminates at the beginning of the 13th month.
That can mean filing a new application instead of simply asking for payments to restart.
The SSA’s SSI suspension regulations explain these distinctions.
When Can Social Security Payments Restart After Release?
Let’s say someone receiving retirement benefits is officially released from prison on October 15.
When should the money return?
Under ordinary Social Security reinstatement rules, November becomes the first month for which benefits can be payable.
But here’s the catch: Social Security generally pays benefits one month after the month they’re owed.
So November’s benefit would normally arrive in December.
That means being released in October doesn’t guarantee a November bank deposit.
Processing delays or other eligibility issues can push the actual deposit even further.
The SSA must verify release information and determine whether the individual still qualifies for benefits.
Its reinstatement instructions explain how these cases are handled.
SSI Recipients May Get Payments Sooner
There’s potentially better news for some SSI recipients.
If someone was receiving SSI before incarceration and their eligibility hasn’t terminated, benefits may resume during the month they’re released.
For example, a person released on September 7 could qualify for a partial SSI payment covering the eligible portion of September.
However, someone whose SSI eligibility already terminated during incarceration generally needs to submit a new application.
New applications follow different payment-start rules, so not everyone receives money covering the release month.
That’s why understanding whether benefits were suspended or terminated makes a big difference.
What Happens to Benefits Paid to Your Family?
Here’s one detail that might bring some relief to families.
If a retired or disabled worker goes to prison, an eligible spouse or child receiving separate Social Security benefits on that worker’s earnings record generally doesn’t lose those payments solely because the worker is incarcerated.
For example, suppose a retired father receives Social Security while his eligible spouse also collects benefits based on his work history.
If his own payments are suspended because of incarceration, his spouse’s benefits may continue.
However, the suspended payment cannot simply be transferred to another family member.
The family member must independently qualify for the benefits they receive.
How to Get Payments Started Again
Getting released is only part of the process. Taking action with Social Security is equally important.
The SSA recommends preparing for reinstatement before leaving jail or prison whenever possible.
Here’s a practical checklist:
- Contact Social Security before release. Ask whether your case requires reinstatement or a new application.
- Get official release documentation. The SSA needs reliable verification of your release.
- Update your contact information. Make sure your mailing address, phone number, and banking details are correct.
- Ask about your payment date. The first payable benefit month and actual deposit date may be different.
- Check for overpayments. Previous debts or recovery deductions could affect your next deposit.
You can contact Social Security at 1-800-772-1213 or find a local office through its official office locator.
If benefits don’t restart, ask whether the agency has verified your release and completed its eligibility review.
What If Social Security Suspended Your Benefits by Mistake?
Mistakes and disagreements can happen.
Perhaps the confinement dates were recorded incorrectly, or Social Security received inaccurate information about the person’s conviction or release.
Affected beneficiaries generally have the right to challenge a suspension decision.
The usual reconsideration deadline is 60 days after receiving the agency’s notice.
Someone facing an overpayment demand can also dispute the amount or request a waiver when the applicable conditions are met.
Don’t ignore an SSA notice simply because the issue appears to be an administrative mistake.
The Bottom Line
Social Security’s incarceration restrictions aren’t a newly introduced 2026 policy, but understanding them remains important.
For regular Social Security benefits, more than 30 continuous days of qualifying confinement can stop payments. Benefits can ordinarily become payable again for the month after release, but the actual money may arrive later.
SSI follows different rules, and some recipients may qualify for payments beginning in their release month.
The simplest way to avoid an unpleasant surprise is to contact Social Security before release, confirm your benefit status, and find out exactly when your payments can legally resume.