7 Brutal Financial Truths That Are Quietly Ruining Your Future
Most people assume working harder will eventually lead to financial stability. But in today’s economy, that belief is quietly breaking down. Salaries aren’t keeping up with reality, debt is becoming a lifelong burden, and the cost of simply existing continues to rise faster than income can match.
The uncomfortable truth is this: many people are not struggling because they are irresponsible—they are struggling because they are following financial patterns that no longer work. And the worst part? These mistakes don’t announce themselves. They build slowly, silently, and consistently until one day, you realize you’re stuck.
Here are 7 brutal financial truths that could already be shaping your future more than you realize.
The Dream of Owning Property is Just a Dream
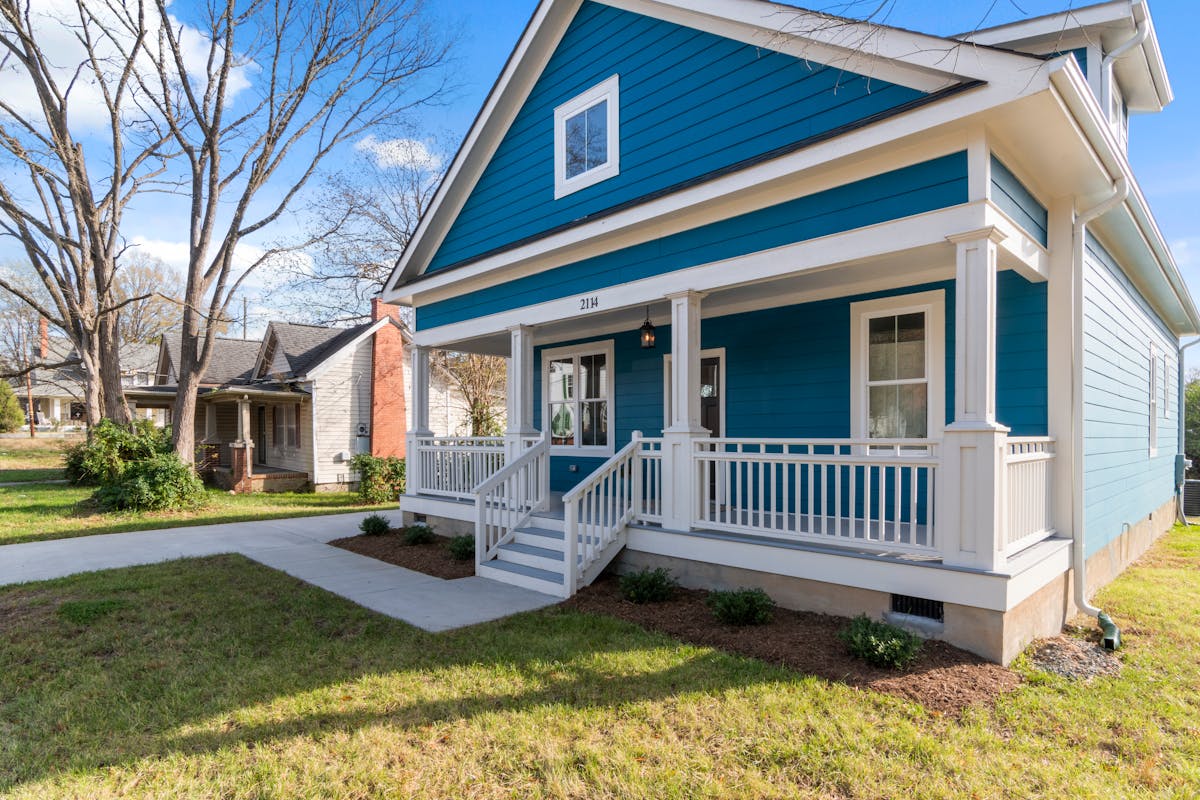
Real estate used to be a cornerstone of financial security, but for many, it’s now out of reach. Property prices have risen exponentially, and what was once an achievable goal is now a luxury few can afford. Even those who manage to buy a home often struggle with mortgage payments and sky-high interest rates.
For most people, homeownership is a dream that will remain unfulfilled. Renting has become the norm for younger generations, while older generations struggle to maintain properties or sell them at a profit due to market saturation.
If buying a home is out of reach, consider long-term renting in affordable areas while building wealth through other investments, such as stocks, bonds, or real estate investment trusts (REITs). Keep an eye on emerging markets that could present more affordable opportunities in the future.
Student Loan Debt is a Weight You’ll Never Escape
Student loan debt is a silent killer of financial freedom. With rising tuition fees and interest rates, many individuals graduate with crippling debt that takes decades to repay, if it’s even possible at all. Even when students land jobs, their salaries are often insufficient to cover their student loan payments and still allow for savings.
This massive debt prevents you from saving for retirement, buying a home, or investing for the future. The interest continues to accumulate, making it harder to pay down the principal, leaving you feeling trapped in a cycle of debt.
Explore income-driven repayment plans, or consider consolidating or refinancing your loans to lower your interest rates. Consider starting to save for retirement early, even if it’s just small contributions. The key is to balance your debt repayment with your financial growth.
Your Salary is No Longer Enough to Live Comfortably

You work hard, earn a steady paycheck, and yet, somehow, it never feels like enough. The truth is that salaries have stagnated while the cost of living continues to climb. In many cities, wages are not keeping pace with the skyrocketing housing, transportation, and healthcare costs.
With your income barely keeping up with the rising cost of living, saving for the future feels impossible. Even if you cut back, it often seems like there’s always something that drains your finances, whether it’s rent, utilities, groceries, or unexpected expenses.
Start looking for ways to boost your income. This could mean taking on a side hustle, investing in new skills for higher-paying opportunities, or exploring passive income streams. You can’t rely solely on your salary in an economy where costs are outpacing wages.
The Stock Market is a Gamble, Not a Safe Bet
Investing in the stock market used to be one of the best ways to build wealth, but today, it’s more like gambling than investing. Market fluctuations, global crises, and unpredictable political events have made it harder to trust the stock market as a reliable source of long-term wealth.
Given the stock market’s volatility, it’s difficult to grow your wealth consistently. If you’re relying on the market to secure your financial future, you’re at the mercy of external forces that you can’t control.
Diversify your investments. Look beyond stocks and consider bonds, real estate, and alternative assets to mitigate risk. Don’t put all your financial eggs in one basket, and focus on building a balanced, long-term portfolio that suits your risk tolerance.
You’re Not Saving Enough for Retirement
Retirement used to feel like something in the distant future. Now, many people are facing retirement with little to no savings. With increased life expectancy and rising healthcare costs, it’s becoming harder to retire comfortably. And it’s too late for many to catch up on savings, even if they start now.
Without sufficient retirement savings, you’ll be forced to work longer or live a much lower standard of living in retirement. Social security benefits are no longer enough to live on, and many people will run out of money long before they run out of years.
Start saving aggressively for retirement, even if you’re behind. Use tax-advantaged accounts like 401(k)s and IRAs, and take advantage of any employer matches. Even small contributions made now will grow over time with compound interest, so don’t wait any longer.
You’re Trapped by High-Interest Credit Card Debt
Credit card debt has become a silent crisis for millions. With high interest rates and minimum payments that barely cover interest, credit card debt is an endless drain on your finances. Many people carry this debt for years, unable to get ahead financially, because of the burden of mounting interest.
Credit card debt can snowball, and it’s hard to get out of this cycle once you’re in. Even if you’re making payments, the interest eats away at your ability to save, invest, or build wealth. This debt holds you back from achieving your financial goals.
Pay off high-interest debt first. Consider using the debt snowball or avalanche method to tackle credit card balances. Also, avoid using credit cards for purchases you can’t afford to pay off in full at the end of each month.
You’re Living Paycheck to Paycheck

No matter how much you earn, if you’re living paycheck to paycheck, it feels impossible to get ahead financially. With minimal savings, no emergency fund, and few assets, any unexpected expense, a car repair, medical bill, or job loss, can throw your financial life into disarray.
Living paycheck-to-paycheck means you have no financial cushion. Even a small setback can lead to significant financial stress and instability, leaving you vulnerable to emergencies or opportunities that require upfront costs.
Build an emergency fund to cover 3-6 months’ worth of expenses. Start small, but make consistent contributions until you have a solid financial safety net. Look for ways to cut unnecessary expenses and boost your income to create breathing room.
Conclusion
Financial collapse rarely feels like a collapse in the beginning. It feels like normal life, working, earning, spending, repeating. That’s what makes these financial truths dangerous. They don’t hit all at once. They accumulate quietly until the pressure becomes impossible to ignore.
By the time most people recognize what’s happening, they are already years behind, locked into debt, rising costs, and financial obligations that leave very little room to recover. But awareness changes the direction of everything.
Because once you can clearly see the patterns that are working against you, you’re no longer moving blindly through them. You can begin to make different choices, smaller adjustments at first, then stronger financial shifts over time.