10 Countries Where Retirement Is Most Likely to Fail
Retirement should mark a time of stability, comfort, and dignity. In these countries, however, it often marks uncertainty, hardship, and risk. Weak pensions, high inflation, poor healthcare, and insufficient social support combine to make old age a struggle rather than a reward for decades of work.
The following countries highlight where retirement security is failing on multiple fronts. In each case, economic, social, and healthcare systems leave older adults exposed, forcing them to rely on family, informal savings, or inadequate public programs.
Greece
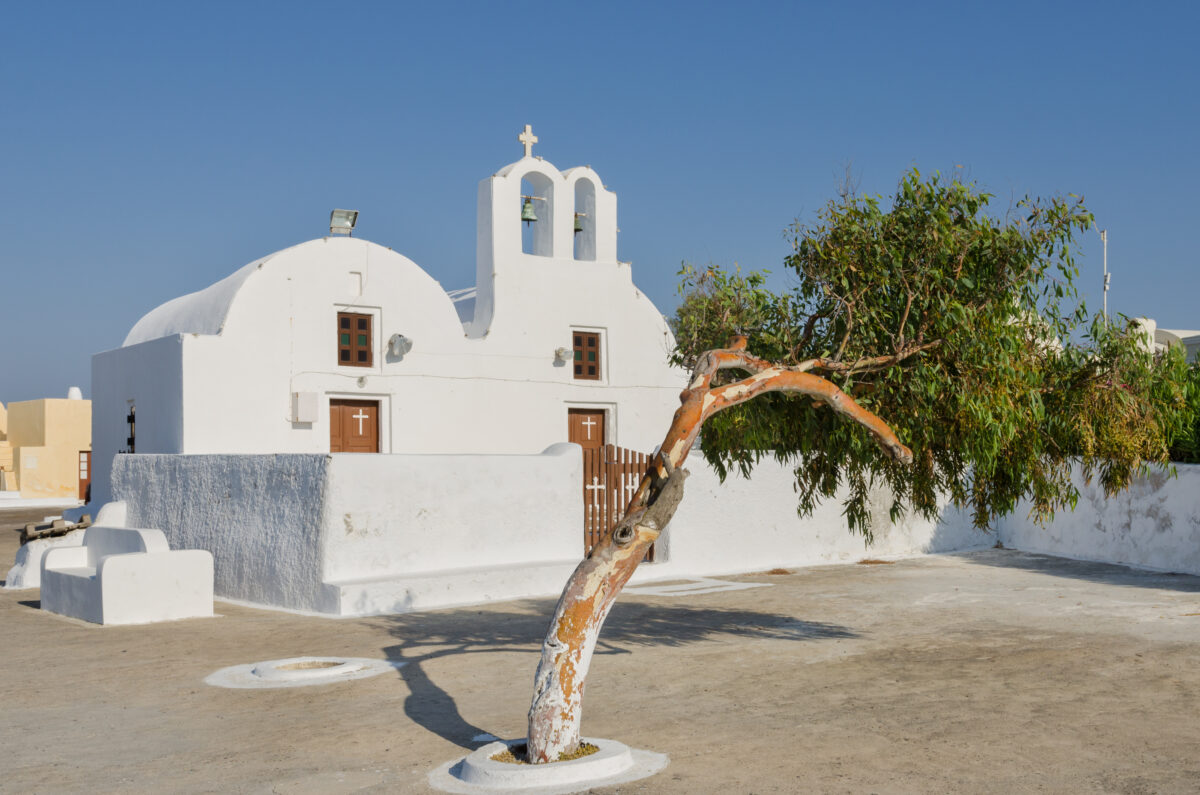
Greece continues to struggle with the long-term effects of the debt crisis and austerity measures. Public pension cuts, economic volatility, and unemployment leave older adults exposed to financial insecurity. Even those with health coverage may find their standard of living eroded by unstable pension payments.
The demographic pressure of an aging population magnifies the risk, as fewer workers support more retirees. Greece shows that retirement systems can fail gradually, eroding security over decades rather than in a sudden collapse.
Mexico
In Mexico, retirement security is uneven and precarious. Millions spend their working lives in informal employment, leaving them without consistent pension contributions. When old age arrives, income gaps and insufficient savings turn retirement into a daily struggle rather than a period of comfort.
Even urban retirees with formal jobs face rising costs and inflation that erode their limited pensions. Rural retirees often rely entirely on family support or sporadic public assistance. Retirement in Mexico exposes the vulnerability of workers who fall outside well-structured systems.
Russia
Russia’s retirement system suffers under economic instability and weak quality-of-life indicators. Pensions exist, but inflation and volatile currency values undermine their purchasing power. Older adults cannot rely solely on public programs, as institutional fragility compounds everyday insecurity.
Confidence in government support is low, leaving many retirees to make difficult choices about healthcare, housing, and daily expenses. Russia shows that a formal pension system alone cannot guarantee retirement security when economic and institutional conditions are unstable.
Chile
Chile’s private pension system creates a stark divide in retirement outcomes. Workers with steady contributions may secure a modest income, but millions with interrupted employment or low wages face serious material shortfalls. Retirees often cannot cover basic living costs despite years of work.
Pension reforms have aimed to improve coverage and benefits, but gaps remain. Material well-being is the country’s weakest link, illustrating how a single vulnerable factor can derail retirement security even when other systems function.
Spain
Spain offers long life expectancy and cultural advantages for retirees, but its financial and material systems are under serious strain. Material well-being is extremely low, forcing many older adults to stretch modest pensions across rising living costs.
Demographic shifts intensify the challenge, as more retirees and fewer working-age contributors enter the system. Retirement in Spain illustrates that a long life alone does not guarantee a secure or comfortable old age.
Brazil
Inequality and informal employment make retirement in Brazil highly unpredictable. Many workers never contribute enough to pension systems, leaving them dependent on family support or government assistance that is often inadequate.
Regional disparities further worsen outcomes, disproportionately affecting rural retirees. Brazil demonstrates that even economic growth cannot guarantee retirement security when labor markets and income distribution are uneven.
China
China faces one of the world’s fastest-aging populations, and traditional family support networks are shrinking. While financial systems are moderately strong, disparities between urban and rural retirees create extreme insecurity for many.
Pension coverage is inconsistent, leaving large segments of the population vulnerable. Aging in China often means navigating insufficient public support while healthcare costs rise, revealing a system unprepared for demographic realities.
Turkey
Turkey’s retirement is highly exposed to economic volatility. Inflation and currency fluctuations can quickly erode savings and pension payouts. Fixed incomes cannot keep up with rising living costs, leaving retirees financially vulnerable.
Even disciplined savers may find their security compromised by national economic instability. Turkey illustrates how macroeconomic risks turn retirement planning into a high-stakes gamble.
Colombia
Colombia suffers from low material wellbeing and limited pension access. Informal employment prevents many workers from building meaningful retirement savings, and public systems cannot fill the gap.
Millions of older adults rely on family networks or minimal government support. Colombia’s situation highlights how labor market instability and weak coverage can turn retirement into financial insecurity rather than a safety net.
India
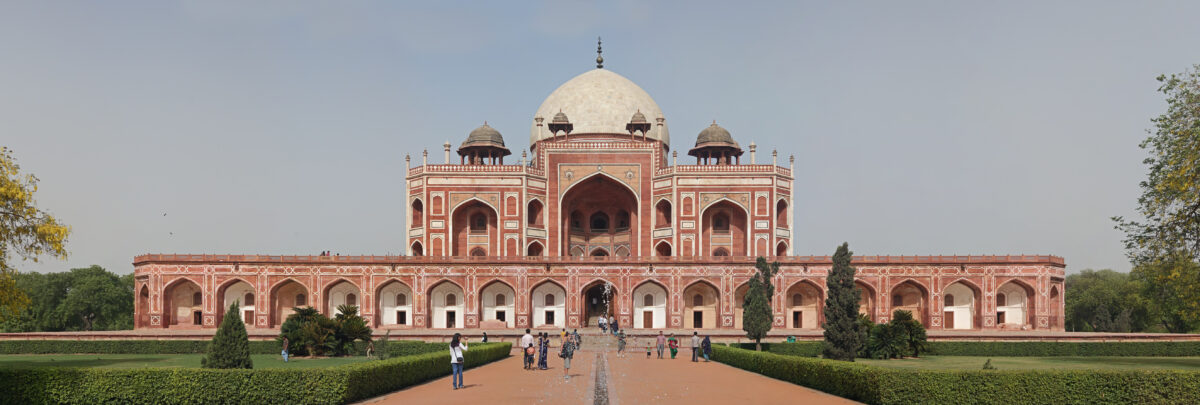
India presents the most extreme case of retirement vulnerability. Millions spend decades in informal employment without access to pensions, healthcare, or sufficient savings. Retirement often relies entirely on family or a small community.
Healthcare costs, weak social safety nets, and demographic pressure exacerbate the challenge. India shows how systemic failures in labor, finance, and health converge to leave older adults dangerously exposed in old age.
Why Retirement Fails in These Countries
The common thread is imbalance. One strong factor, such as health, pensions, or quality of life, cannot compensate for weakness in others. Informal labor, economic volatility, inequality, demographic pressure, and limited healthcare access all magnify retirement risk.
These countries demonstrate that retirement security requires stability across multiple systems. Weak coverage, insufficient income, and inadequate social supports mean old age is uncertain for millions.
Conclusion
Retirement security is not guaranteed by pensions alone. It depends on consistent contributions, financial stability, material well-being, healthcare access, and quality of life. Countries where these pillars are weak expose millions to poverty and hardship.
Informal labor markets and inequality amplify vulnerability. Women, rural workers, and low-income populations face the harshest consequences, often lacking the support networks or savings to mitigate risk.
Policymakers and individuals must recognize that retirement planning starts decades before old age. Strengthening pensions, stabilizing economies, expanding healthcare access, and ensuring income equality are critical to preventing retirement from failing at the worst possible moment.