Scott Bessent Says the K-Shaped Economy Is Over, But Data Shows America’s Economic Divide Is Far From Settled
Treasury Secretary Scott Bessent says America has moved beyond the “K-shaped economy,” arguing that lower-income workers are finally sharing in the nation’s economic recovery. But a closer look at wage growth, household spending, stock market gains, and wealth distribution shows a more complicated picture, with some signs of improvement alongside persistent economic gaps.
Bessent’s claim has reignited a major debate among economists over whether America’s recovery is becoming more inclusive or whether the benefits of growth are still concentrated among households with the strongest financial foundations. While some workers have seen meaningful wage increases, many families continue facing challenges tied to housing costs, inflation pressures, and limited access to wealth-building assets.
The disagreement highlights a larger question shaping the U.S. economy: Is growth becoming broad-based, or are different groups still experiencing entirely different financial realities?
Scott Bessent Declares the K-Shaped Economy Is Finished
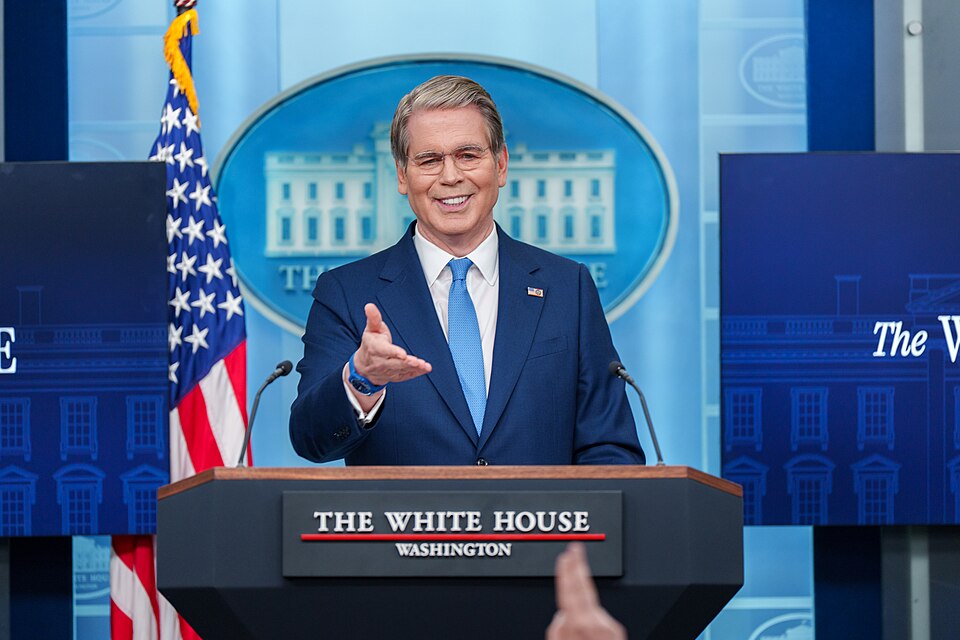
Scott Bessent has rejected the idea that America remains divided between households benefiting from economic growth and those falling behind. Speaking about current economic conditions, the Treasury secretary argued that the K-shaped economy is no longer an accurate description and said lower-income workers are finally experiencing stronger gains.
Instead, Bessent described what he called a “C-shaped economy,” where different income groups are moving upward together. He pointed to wage improvements among lower-income workers and highlighted policies under the Trump administration, including changes affecting overtime pay, tips, and Social Security taxes, as examples of measures improving household finances.
Bessent specifically pointed to data showing lower-income workers experienced real wage gains. Treasury figures cited by the secretary indicated blue-collar workers saw wage growth of roughly 1.7% during the first months of the administration, while Bessent argued the lowest 25% of workers had experienced about a 2% real wage improvement.
However, economists say wage growth represents only one piece of the economic picture. A household’s financial health also depends on wealth, housing ownership, investment access, debt levels, and whether income gains are keeping pace with everyday expenses.
Wage Growth Shows Progress, But the Gap Has Not Completely Disappeared
Lower-income workers have experienced stronger wage growth compared with the years before the pandemic, providing support for Bessent’s argument. Labor shortages after COVID-19 forced many employers to increase pay, especially in industries such as restaurants, transportation, manufacturing, and retail.
The Atlanta Federal Reserve’s Wage Growth Tracker has shown that lower-wage workers benefited from some of the strongest wage increases during the post-pandemic period. Its income quartile analysis found that workers in the lowest quartile experienced wage growth, although the data has not consistently shown them outperforming higher earners.
The Atlanta Fed’s June update showed the lowest quartile of wage earners recorded approximately 3.6% wage growth, while the highest quartile saw around 3.9%. The figures suggest that while lower-income workers are gaining ground, the wage divide has not completely disappeared.
The challenge is that stronger wages do not automatically create stronger wealth. A worker earning more money today may still struggle to build long-term financial security if housing, healthcare, and other costs consume most of that additional income.
The Stock Market Boom Continues to Create a Wealth Divide
One of the biggest challenges to the idea that the K-shaped economy has ended is the continued strength of financial markets. The artificial intelligence boom has pushed technology stocks higher, creating enormous gains for investors and households with significant exposure to equities.
The problem is that stock ownership remains heavily concentrated among wealthier Americans. Federal Reserve data has consistently shown that the highest-income households own the majority of stocks, mutual funds, and other financial assets.
Economists argue that this creates a major difference between households that benefit from market growth and those that depend mainly on wages. When the stock market rises, investors gain wealth quickly, while many workers without substantial investments may see little direct improvement.
Joe Brusuelas, chief economist at RSM, has noted that much of the wealth created through equity gains flows toward higher-income households. He argued that relying on stock market growth to support consumer strength can reinforce existing economic divisions rather than eliminate them.
The AI Boom Created New Fortunes, But Not Everyone Has Access
Artificial intelligence has become one of the strongest drivers of recent economic optimism. Companies connected to AI technology, semiconductor production, and data infrastructure have experienced massive investor enthusiasm, creating significant gains for shareholders.
For investors who entered the AI market early, the economic impact has been substantial. Rising valuations have increased wealth among individuals and institutions that already had access to capital and financial markets.
However, the broader workforce has not experienced the same immediate benefits. Many workers outside technology-related industries have yet to see significant changes in wages or job opportunities connected to artificial intelligence.
Economists believe AI could eventually increase productivity and create broader economic benefits. But history suggests that major technological transformations often create concentrated wealth first before those gains spread throughout the wider economy.
Housing Remains One of America’s Biggest Economic Divides
Housing continues to be one of the clearest examples of how economic gains have been distributed unevenly. Americans who purchased homes before prices surged benefited from rising property values, increased equity, and one of the largest wealth-building opportunities available to households.
Homeownership has historically been one of the biggest drivers of middle-class wealth. Families who own property can build equity over time, while rising home values can provide financial security, borrowing power, and retirement advantages. Renters have faced a much different reality. Higher rents, limited housing supply, and elevated mortgage rates have made it harder for many younger and middle-income Americans to purchase homes.
This divide has become a major part of the K-shaped economy debate because asset ownership determines who benefits from rising prices. Homeowners often gain wealth from inflation in property values, while renters frequently experience the same trend as a financial burden.
Generational Wealth Differences Continue Shaping Economic Outcomes
The economic divide is also closely connected to age. Older Americans are more likely to own homes, retirement accounts, and investment portfolios that have benefited from decades of asset appreciation. Federal Reserve wealth data has shown that older generations hold a significant share of America’s household wealth. Many benefited from entering housing and financial markets before prices increased dramatically.
Younger Americans entered the economy under different conditions. Many face higher housing prices, larger education expenses, and increased living costs that make saving and investing more difficult. Even when younger workers receive wage increases, they often start from a disadvantage because fewer assets are available to generate additional wealth. This creates a situation where two generations can both experience economic growth differently.
Consumer Spending Reveals the Uneven Recovery
Consumer spending remains a critical measure of economic strength, but spending patterns show how differently households experience financial conditions. Higher-income Americans often have more flexibility because they have savings, investments, and access to credit. Recent analysis has shown that households earning more than $200,000 annually have continued increasing their spending at a much stronger pace.
Moody’s chief economist Mark Zandi cited Federal Reserve data showing spending among these households grew significantly, while spending among the bottom 80% remained much weaker after adjusting for inflation. This difference matters because consumer spending drives much of the U.S. economy.
When wealthier households increase spending, businesses benefit, but the impact does not necessarily mean financial conditions are improving equally for everyone. Lower-income households typically spend a larger share of their income on necessities. When prices rise, they have fewer options to absorb those increases.
Tax Policies Add Another Layer to the Economic Debate
Bessent has argued that recent tax policies are improving household finances by increasing take-home pay for working Americans. Supporters point to changes involving tips, overtime income, and other provisions as examples of policies designed to provide direct financial relief.
The White House has argued that the One Big Beautiful Bill Act would provide significant tax benefits for working families. Supporters say these changes could increase disposable income and encourage consumer spending. However, economists remain divided over how much impact tax changes will have on broader economic inequality.
Critics argue that additional income may provide temporary relief but does not necessarily solve deeper challenges involving housing affordability, wealth inequality, and access to investments. The long-term question is whether households can use additional income to build savings and assets or whether higher costs will continue absorbing those gains.
Bank of America Sees Signs of Improvement, But Economists Remain Cautious
Some economic indicators do support Bessent’s argument that parts of the K-shaped economy may be narrowing. Bank of America economists have noted that consumer spending differences between income groups have recently become less divided in certain measurements.
Economist Aditya Bhave identified several possible reasons, including stronger job growth, lower tax withholding, declining gasoline prices, and favorable comparisons with previous periods when spending gaps were wider. However, economists caution that short-term improvements do not necessarily mean a permanent shift.
A few months of stronger spending among lower-income households may not be enough to prove that long-standing wealth differences have disappeared. The broader data still shows major differences in asset ownership, investment gains, and household financial security.
The K-Shaped Economy Debate Is Not Over Yet
The question of whether the K-shaped economy has ended depends largely on which economic indicators receive the most attention. Wage data suggests lower-income workers have made real progress, while wealth data shows that asset ownership remains concentrated among higher-income households.
Both realities can exist at the same time. The economy can improve while millions of Americans continue feeling pressure from high costs and limited opportunities to build wealth. The debate continues because economists are measuring different parts of American financial life. Some focus on income and employment, while others focus on wealth accumulation and long-term security.
The next phase of the recovery will reveal whether today’s improvements become lasting changes or whether the divide between asset owners and wage earners remains a defining feature of the American economy.
The Real Test Is Whether More Americans Can Build Wealth
The future of the economy will not be judged only by wage growth, tax changes, or stock market performance. The deeper measure will be whether more Americans can purchase homes, build savings, invest for retirement, and create financial stability.
A truly broad recovery would mean more households gaining access to the assets that have historically separated financially secure Americans from those living paycheck to paycheck. For now, Scott Bessent’s claim has sparked an important economic debate, but the evidence remains mixed.
Some Americans are clearly benefiting from the recovery, while others are still waiting for growth to reach their everyday lives. The question is no longer simply whether the economy is expanding, but whether prosperity is spreading widely enough for more Americans to feel it.